
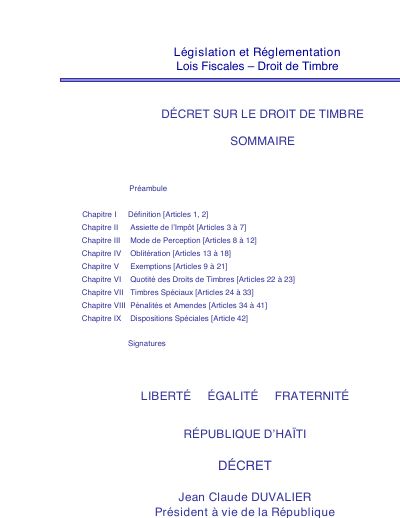
Decree on Stamp Duty
Summary: The stamp-duty decree, in the MEF's Lois Fiscales series. Forty-one articles across ten chapters cover the definition, the tax base, the mode of collection, cancellation, exemptions, the scale of duties, special stamps, and penalties and fines.
Key Findings
- Forty-one articles across ten chapters.
- Chapter II fixes the tax base at articles 3 to 7; Chapter VI sets the scale of duties.
- Chapter VII covers special stamps at articles 24 to 33.
- Chapter VIII covers penalties and fines at articles 34 to 41.
- It is the instrument behind a recurring revenue line in the Haitian budget.
Full Description
The decree on stamp duty, reproduced in the Ministry of Economy and Finance's Lois Fiscales compilation.
The structure is set out in its sommaire: Chapter I defines the duty, Chapter II fixes the tax base across articles 3 to 7, Chapter III the mode of collection, Chapter IV cancellation, Chapter V exemptions, Chapter VI the scale of duties, Chapter VII special stamps across articles 24 to 33, and Chapter VIII penalties and fines across articles 34 to 41.
Stamp duty is one of the small recurring revenue lines that appear in every Haitian budget and is rarely traced back to its instrument. This is that instrument.
How to cite
Ministry of Economy and Finance (MEF), 1978, Decree on Stamp Duty, https://www.mef.gouv.ht/
- Rights holder
- Government of Haiti