
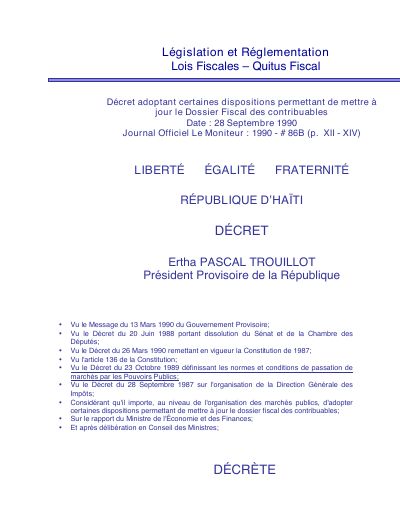
Decree of 28 September 1990 on the Tax Clearance Certificate (Quitus Fiscal)
- Article 1 makes a tax clearance certificate a condition of admissibility for any public-procurement bid.
- Article 2 applies the requirement whatever the amount, category or method of award.
- Article 3 has the DGI issue the certificate to taxpayers in good standing.
- Article 4 sets the fee at 250 gourdes.
- Article 5 preserves the separate requirements for the built-property tax discharge certificate, issued free, and the land-registry certificate, issued for a fee.
- It is the mechanism by which tax arrears exclude a firm from state contracts.
The decree of 28 September 1990, published in Le Moniteur No. 86-B of 1990, conditioning public procurement on tax compliance.
Article 1 obliges bidders for a public contract organised by the state or a public enterprise to attach their tax clearance certificate for their submission to be admissible. Article 2 makes the requirement a prerequisite to any document of presentation or accreditation in a procurement, whatever the amount, the category or the method of award. Article 3 has the DGI issue the certificate to any taxpayer in good standing with the revenue. Article 4 sets the fee at 250 gourdes. Article 5 provides that the quitus does not dispense the bidder from producing the tax-discharge certificate for the built-property tax, issued free of charge, or the land-registry certificate, issued for a fee.
The instrument matters because it is the point at which the procurement system and the revenue system are joined: it is the mechanism by which tax arrears exclude a firm from state contracts.
How to cite
Presidency of the Republic of Haiti (PRH), Decree of 28 September 1990 on the Tax Clearance Certificate (Quitus Fiscal), https://www.mef.gouv.ht/
- Rights holder
- Government of Haiti