
Governor's Letter to the Professional Association of Banks on Loan-Loss Provisions and the IFRS Transition, September 8, 2008
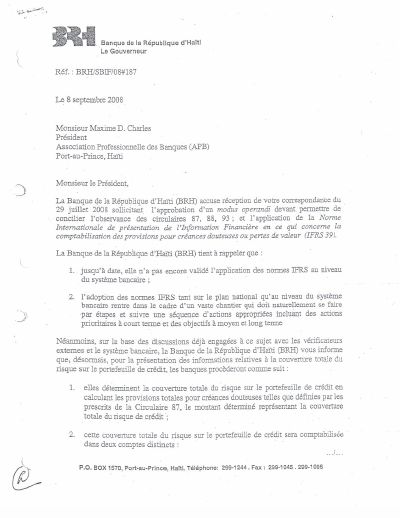
- As of the letter, the BRH had not validated the application of IFRS in the banking system, and adoption is to proceed in stages.
- Banks compute total credit-risk coverage as the total provisions for doubtful receivables defined by circular 87.
- Provisions on weak, doubtful and loss loans are booked on the balance sheet as loan-loss provisions.
- The general provision on watch-list and current loans is deducted from retained earnings and recorded in equity as a general reserve for loan losses that cannot be distributed.
- The general reserve is not counted in Tier 1 capital under circular 88, and the arrangement replaces the circular 93 rule on provisions for doubtful receivables.
The Governor acknowledges a letter of July 29, 2008 from the president of the Professional Association of Banks (APB) asking for approval of a modus operandi that reconciles circulars 87, 88 and 93 with the international financial reporting standard on provisions for doubtful receivables. The BRH recalls that it has not yet validated the application of IFRS in the banking system and that adoption is a staged process.
It then sets how banks present total credit-risk coverage: provisions on weak, doubtful and loss loans under circular 87 stay on the balance sheet as loan-loss provisions, while the general provision on watch-list and current loans is deducted from retained earnings and shown in equity under a new non-distributable line, the general reserve for loan losses. That reserve is excluded from Tier 1 capital under circular 88, and the arrangement replaces the circular 93 rule on provisions for doubtful receivables.
How to cite
Bank of the Republic of Haiti (BRH), Governor's Letter to the Professional Association of Banks on Loan-Loss Provisions and the IFRS Transition, September 8, 2008, https://www.brh.ht/wp-content/uploads/2018/08/note_ifrs_2008.pdf
- Rights holder
- Banque de la République d'Haïti (BRH)