
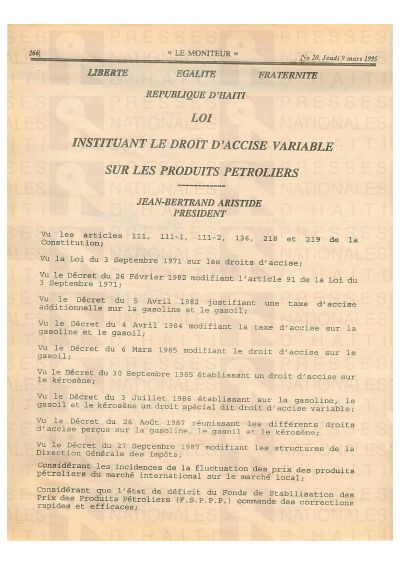
Law of 5 February 1995 Instituting the Variable Excise Duty on Petroleum Products
- The duty is variable by construction: it is the residual between the landed cost of imported fuel and the administered pump price.
- It rises when world prices fall and compresses or turns negative when they rise while the pump price is held.
- It is the statutory basis for the monthly MEF petroleum price structures the corpus already holds.
- A pump-price adjustment is therefore a budget event.
- The corpus held the instrument's outputs and the arguments about it, but not the instrument itself.
The law of 5 February 1995 instituting the variable excise duty on petroleum products, recovered from the SGCM archive.
The duty is variable by design: it is the residual between the landed cost of imported fuel and the administered pump price, so it rises when world prices fall and compresses, or turns negative, when they rise and the government holds the pump price. That mechanism is why fuel pricing sits at the centre of every Haitian fiscal negotiation, why the corpus's monthly petroleum-product structures matter, and why a pump-price adjustment is a budget event.
The corpus holds the monthly MEF price structures that apply this duty and the analyses that argue about it, but not the instrument that created it.
How to cite
Legislative Body of Haiti, Law of 5 February 1995 Instituting the Variable Excise Duty on Petroleum Products, https://www.mef.gouv.ht/
- Rights holder
- Government of Haiti