Description Complète
L'unité Analyse et cartographie de la vulnérabilité du Programme alimentaire mondial publie ce bulletin de suivi des marchés pour Haïti. Cette édition couvre avril et mai 2026.
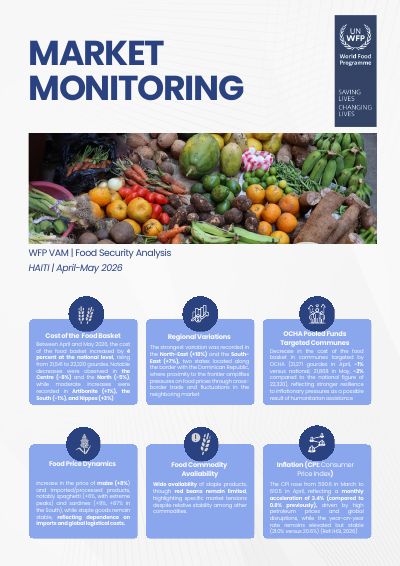
Le coût du panier alimentaire national augmente de 4 pour cent sur les deux mois, de 21 541 à 22 320 gourdes. Le mouvement est inégal selon les départements : le Nord-Est progresse de 18 pour cent et le Sud-Est de 7 pour cent, tous deux sur la frontière dominicaine où le commerce transfrontalier et le marché voisin transmettent la pression sur les prix, tandis que le Centre recule de 8 pour cent et le Nord de 5 pour cent. Les communes ciblées par les fonds communs d'OCHA enregistrent un panier inférieur de 1 pour cent au niveau national en avril et de 2 pour cent en mai, ce que le bulletin lit comme un indice possible de l'effet amortisseur de l'aide humanitaire.
Parmi les produits, le maïs augmente de 8 pour cent et les biens importés ou transformés davantage encore, le spaghetti de 6 pour cent et la sardine de 9 pour cent au niveau national et de 87 pour cent dans le Sud, tandis que les autres denrées de base restent globalement stables.
Sur la disponibilité, les commerçants déclarent une offre satisfaisante de farine de blé, de riz, de maïs, de sucre, d'huile végétale et de haricot noir. Le haricot rouge fait exception : 52 pour cent des commerçants le déclarent absent ou en quantité limitée, avec des niveaux critiques dans les Nippes à 87,5 pour cent, le Nord-Est à 84,6 pour cent, le Sud-Est à 64,7 pour cent et le Nord à 60 pour cent. Le sel manque dans l'Artibonite et les Nippes, les œufs dans les Nippes et le Sud-Est, le spaghetti dans le Centre et le Nord-Est. Le Sud-Est présente une indisponibilité élevée sur presque tous les produits enquêtés.
Sur l'inflation, l'indice des prix à la consommation passe de 590,6 en mars à 610,5 en avril, soit une accélération mensuelle à 3,4 pour cent contre 0,8 pour cent, que le bulletin attribue au prix élevé des produits pétroliers et aux perturbations mondiales. L'inflation en glissement annuel s'établit à 21,0 pour cent contre 20,6 pour cent, élevée mais stable.
Texte Intégral du Document
Texte extrait du document original pour l'indexation.
MARKET
MONITORING
Timmerman
Industries
WFP VAM | Food Security Analysis
HAITI | April-May 2026
Cost of the Food Basket
Between April and May 2026, the cost
of the food basket increased by 4
percent at the national level, rising
from 21,541 to 22,320 gourdes. Notable
decreases were observed in the
Centre (-8%) and the North (-5%),
while moderate increases were
recorded in Artibonite (+1%), the
South (-1%), and Nippes (+3%)
Regional Variations
The strongest variation was recorded in
the North-East (+18%) and the SouthEast (+7%), two states located along
the border with the Dominican Republic,
where proximity to the frontier amplifies
pressures on food prices through crossborder trade and fluctuations in the
neighboring market
OCHA Pooled Funds
Targeted Communes
Decrease in the cost of the food
basket in communes targeted by
OCHA (21,271 gourdes in April, -1%
versus national; 21,868 in May, -2%
compared to the national figure of
22,320), reflecting stronger resilience
to inflationary pressures as a possible
result of humanitarian assistance
Food Price Dynamics
Food Commodity
Availability
Inflation (CPI: Consumer
Price Index)
Increase in the price of maize (+8%)
and imported/processed products,
notably spaghetti (+6%, with extreme
peaks) and sardines (+9%, +87% in
the South), while staple goods remain
stable, reflecting dependence on
imports and global logistical costs.
Wide availability of staple products,
though red beans remain limited,
highlighting specific market tensions
despite relative stability among other
commodities.
The CPI rose from 590.6 in March to
610.5 in April, reflecting a monthly
acceleration of 3.4% (compared to
0.8% previously), driven by high
petroleum
prices
and
global
disruptions, while the year-on-year
rate remains elevated but stable
(21.0% versus 20.6%) (Ref: IHSI, 2026)
�Food Commodity Availability – May
2026
The analysis highlights a generally satisfactory
availability of staple food commodities such as
wheat flour, rice, maize, sugar, vegetable oil, and
black beans, with traders reporting only minor
proportions of unavailability. In contrast, red beans
stand out for their pronounced scarcity: more than
half of traders (52%) reported absence or limited
availability, underscoring their vulnerability within
market equilibrium and their critical role in
household diets.
At the state level, staple food availability remains
broadly stable, but red beans concentrate the most
acute tensions. The Nippes (87.5%), North-East
(84.6%), South-East (64.7%), North (60%), as well
as Artibonite and West (over 40%) display critical
levels of unavailability. This pattern contrasts
sharply with black beans, which remain widely
accessible across most departments, except in the
Centre and Grand’Anse where occasional
limitations were observed.
Beyond beans, certain commodities reveal specific
regional fragilities. Salt shows high unavailability in
Artibonite (36.1%) and Nippes (31.25%), while eggs
are constrained in Nippes (25%) and South-East
(17.65%). Processed imports such as spaghetti also
face localized shortages, notably in the Centre
(8.3%) and North-East (7.7%).
The South-East emerges as the most vulnerable
department with elevated unavailable rates across
Timmerman
nearly all surveyed products thus
reflecting
structural weaknesses in its local Industries
market and
heightened exposure to supply chain disruptions.
These findings point to a dual reality: while the
national food system maintains a relatively stable
supply of core staples, the persistent scarcity of red
beans and other commodities expose structural
vulnerabilities. These imbalances highlight the need
for targeted interventions to stabilize availability,
particularly in departments where deficits are most
severe.
Figure 1: Proportion of traders reporting limited availability of food
products
Vegetable oil
6%
Rice
4% Maize
4%
Black Beans
7%
Red Beans
52%
Source: WFP, 2026
Brand Awareness
Figure 2: Proportion of traders by department reporting limited
availability of food products
Wheat flour
Rice
Maize
Sugar
Black Beans
Red Beans
Vegetable Oil
100%
80%
60%
40%
20%
Source: WFP, 2026
Ea
st
So
ut
h
So
ut
h
W
es
t
W
es
t
No
rt
h
Ea
st
No
rt
h
No
rt
h
Ni
pp
es
G
ra
nd
'A
ns
e
C
en
tr
e
Ar
tib
on
ite
0%
�Price trends for staple foods – AprilMay 2026
Timmerman
Industries
The analysis of price variations between April and May 2026 highlights a dual dynamic. On the one hand, staple
products such as wheat flour, rice, sugar, vegetable oil, and salt show an overall trend of decline or stability,
which helps to limit inflationary pressure on households. Black beans decreased slightly, while red beans
increased marginally, though with significant regional disparities. This relative stability reflects sufficient
availability and a certain balance in the markets for essential goods.
On the other hand, some commodities are experiencing marked increases that are directly linked to fuel
inflation. Maize rose by an average of +8%, with peaks in the Centre (+21%), North-East (+17%), North-West
(+18%), and South (+16%). Imported and processed products are particularly volatile: spaghetti increased by
+6% overall but surged in the West (+54%). Sardines follow the same pattern (+9%), driven by a sharp increase
in the South (+87%). These price increase reflects a strong dependence on external markets and logistical costs,
increasing household vulnerability to global shocks.
From a strategic perspective, these findings suggest that inflationary pressure is driven primarily by imported
and processed products, while local staple goods partly cushion the impact. To contain inflation, it would be
crucial to strengthen national production of cereals and legumes, diversify sources of supply, and implement
price regulation mechanisms for sensitive imported goods.
At the same time, reinforce and monitor regional market prices to anticipate imbalances and protect household
food security.
Figure 3: Price variation of food commodities, April–May 2026 (four
commodities with significant changes)
Maize
40%
Sugar
Red Beans
Salt
Brand Awareness
30%
20%
10%
0%
-10%
-20%
Source: WFP, 2026
Ea
st
So
ut
h
So
ut
h
W
es
t
W
es
t
No
rt
h
Ea
st
No
rt
h
No
rt
h
Ni
pp
es
G
ra
nd
'A
ns
e
C
en
tr
e
Ar
tib
on
ite
-30%
�Food basket– April-May 2026
Timmerman
Industries
Source: WFP, 2026
Between April and May 2026, the cost of the food basket increased by a national average of 4%, rising from
21,541 to 22,320 gourdes, with significant regional disparities: some areas such as the Centre (-8%) and the
North (-5%) recorded declines, while other departments witnessed moderate increases, such as Artibonite
(+1%), the South (-1%), and Nippes (+3%). However, the most marked changes were observed in the NorthEast (+18%) and the South-East (+7%), two departments bordering the Dominican Republic. This suggests
that their proximity to the border has amplified pressure on food prices, likely linked to cross-border trade, the
availability of imported goods, and food price fluctuation in the neighboring market. This dynamic explains
why, despite an overall upward trend, some border regions are experiencing much sharper increases than
the rest of the country.
In April,
the food
basket in communes targeted by the OCHA pooled funds stood at 21,271 gourdes,
Brand
Awareness
representing a 1% decrease compared to the national average (21,541 gourdes). In May, the gap widened to
2%, with 21,868 gourdes in OCHA pooled fund intervention communes compared to 22,320 gourdes at the
national level.
This trend shows that communes targeted by the OCHA pooled funds may benefit from increased
resilience to inflation, thanks to better stabilization of food prices. Strategically, this should highlight the
importance of humanitarian funding in cushioning price increases and reducing household vulnerability
�Description of Methodological approach of market monitoring
The methodology used is that of the Joint Market Monitoring Initiative (JMMI) for harmonization purposes
within the systems used by other actors in the Cash Working Group (CWG).
Data are collected twice a month (1st and 4th weeks of the month) through face-to-face interviews with
five (5) traders per product in each market. In total, 534 traders across 71 markets were surveyed.
All ten (10) departments were covered by the data collection, including the Port-au-Prince Metropolitan
Area.
A minimum of six (6) markets per department were selected based on their level of importance.
Selection of products and units of measurement
The selection of products included in the food basket is based on the Minimum Expenditure Basket (MEB). It
focuses on seven (7) staple products that make up the food basket of Haitian households, taking into
account the energy needs of a household of five (5) people (2,100 kcal requirement).
Wheat flour (30 kg);
Rice (20 kg); maize meal (10 kg);
Sugar (3 kg);
Black beans (10 kg);
Red beans (10 kg);
Vegetable oil (1.5 gallons).
Additionally, other products are included based on their regular consumption by households, namely:
salt, spaghetti, sardines, and eggs. Data collection is conducted on a monthly basis.
Data collection tools
Mobile Operational Data Acquisition (WFP Data Collection Platform).
Limitations and challenges
The limited availability of certain traders, especially wholesalers during periods of high demand for specific
products in certain markets may have hindered the ability to reach the planned sample sizes in some areas,
thereby reducing the accuracy of the estimates
WFP| Haïti
Lauren LANDIS, Country Director
Erwan RUMEN , Deputy Country Director
Technical Team:
Telesphore OUEDRAOGO, Head of RAM unit
Wilfried CHIGBLO, VAM officer
Kendy MASSENA, VAM Associate
Samuel BEAUSEJOUR, GIS Associate
Contact : telesphore.ouedraogo@wfp.org
@WFP_Haiti
�